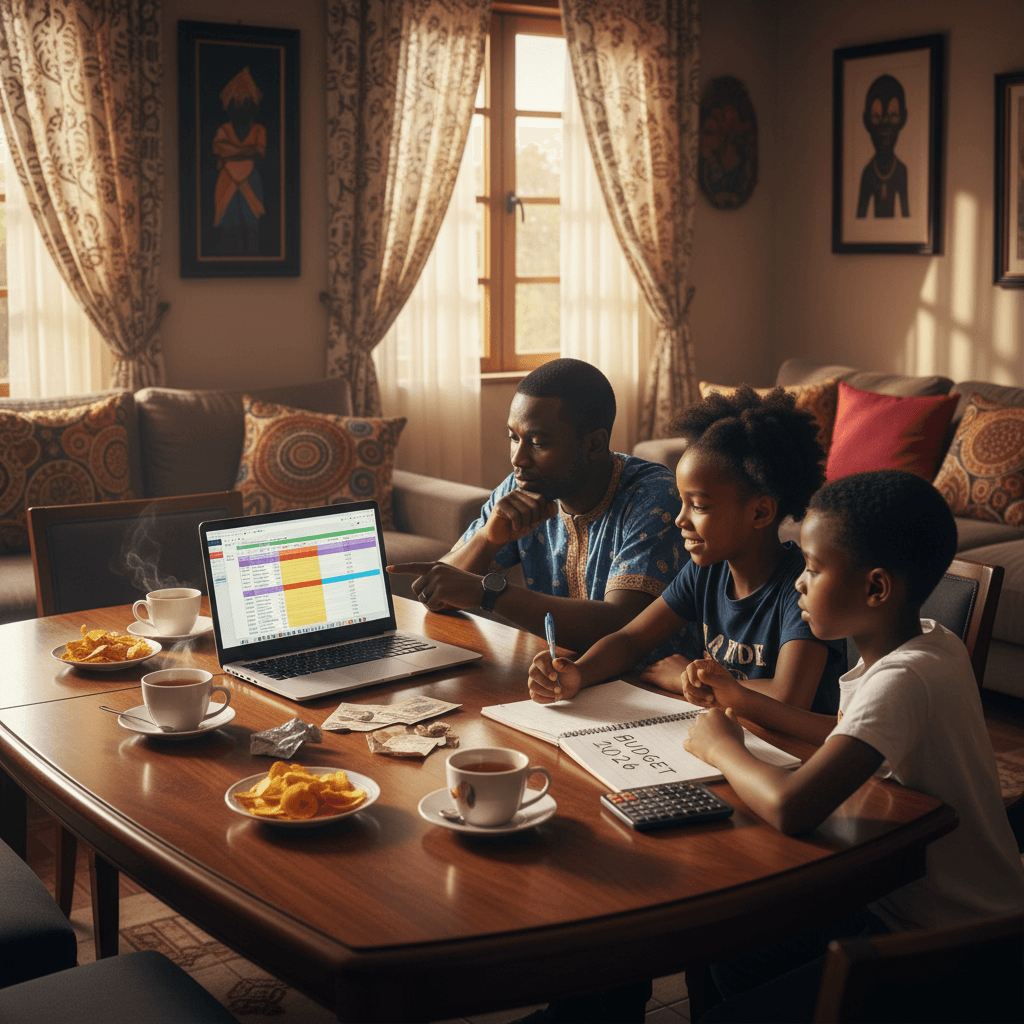
Monthly Budget Template for Nigerian Households in 2026
Monthly Budget Template for Nigerian Households in 2026
Navigating the Nigerian economy in 2026 requires more than just hard work; it demands smart financial planning. With persistent inflation, fluctuating exchange rates, and the continuous rise in the cost of living, creating and sticking to a monthly budget isn't just an option – it's a survival strategy for every Nigerian household. This comprehensive guide will provide you with a practical, adaptable budget template specifically designed for the realities of 2026, helping you take control of your finances, save for your future, and achieve financial stability despite the challenges.
Many Nigerian families often find themselves asking, "Where did all the money go?" or "How can we save anything with things so expensive?" These are valid concerns. As of early 2026, the National Bureau of Statistics (NBS) indicates that headline inflation hovers around 28%, making every naira stretch less than it did a year ago. Fuel prices, though somewhat stabilized, remain significantly higher than pre-subsidy removal levels, averaging ₦750-₦800 per litre in major cities like Lagos and Abuja. The exchange rate, while volatile, generally hovers around ₦1,250 to ₦1,300 per US dollar, impacting the cost of imported goods from foodstuffs to electronics. These economic realities make a robust budgeting framework non-negotiable for households striving for financial peace.
This article isn't just about listing expenses; it's about empowering you with a system to allocate your resources effectively, identify areas for cost-cutting, and build a foundation for wealth creation. Whether you're a young couple starting out, a growing family, or a single earner supporting dependents, this template and accompanying advice will serve as your blueprint to financial discipline in the Nigerian context.
Why a Monthly Budget Template is Essential for Nigerian Households in 2026
A monthly budget template is essential for Nigerian households in 2026 because it provides a clear roadmap for managing income and expenses amidst economic uncertainties like high inflation and rising living costs. It helps families allocate their limited resources effectively, identify spending leaks, and ensure funds are available for critical needs, savings, and future goals.
In a landscape where economic shocks are common and the value of the naira often fluctuates, operating without a budget is like sailing without a compass. The current economic climate, characterized by a high cost of living, means that every kobo counts. Without a structured plan, it's easy for money to disappear on unplanned expenses, leaving little for savings or emergencies. This often leads to the dreaded "sapa" feeling before the month even ends.
A well-crafted budget serves multiple critical functions for a Nigerian household:
- Financial Clarity: It gives you a clear picture of exactly where your money comes from and where it goes. No more guessing games or wondering why your account balance is low.
- Debt Reduction: By identifying surplus funds or areas to cut back, you can channel more money towards paying off high-interest debts, like personal loans or credit card balances, which often come with rates upwards of 30-40% per annum from commercial banks.
- Increased Savings: A budget allows you to intentionally set aside money for an emergency fund, future investments, or significant purchases like school fees, a new car, or even land. Without a budget, savings often become an afterthought.
- Goal Achievement: Whether it's saving for a child's university education, buying a plot of land in Ibeju-Lekki, or starting a small business, a budget turns abstract dreams into actionable financial steps.
- Reduced Financial Stress: Knowing you have a plan and are in control of your money significantly reduces anxiety and arguments related to finances within the household.
- Improved Spending Habits: Over time, budgeting helps you identify unnecessary spending patterns and encourages more mindful consumption, leading to better financial habits for the entire family.
Think of your budget as your financial shield against unpredictable economic headwinds. It's a proactive tool that empowers you to make informed decisions, rather than reacting to financial pressures. With the price of everything from a loaf of bread to generator fuel constantly on the rise, having a clear financial plan for your household is no longer a luxury, but a necessity.
Understanding Your Income: The Foundation of Your Nigerian Household Budget
Understanding your household's total net income is the foundational step for any effective budget, as it dictates the total amount of money available for allocation to expenses, savings, and debt repayment. This involves accurately calculating all regular and irregular earnings after taxes and deductions, providing a realistic figure to work with.
Before you can begin to allocate funds, you need to know exactly how much money your household brings in each month. This isn't just about your salary; it encompasses all sources of income for every working member of the household. It's crucial to use your net income – the amount that actually hits your bank account after deductions like PAYE tax, pension contributions, and any other statutory levies. Do not budget based on your gross income, as this will lead to an inflated and unrealistic budget.
Key Income Sources to Consider:
- Salaries: For all working adults in the household, use the take-home pay.
- Business Income: If anyone runs a small business (e.g., selling clothes online, a provision shop, a mechanic workshop), estimate the average monthly net profit after deducting business expenses.
- Side Hustles: Earnings from freelance gigs, consulting, weekend jobs, or services like driving for ride-hailing apps.
- Rental Income: If you have property generating rent, include the net income after expenses like maintenance or agent fees.
- Investment Income: Dividends, interest from fixed deposits, or returns from Treasury Bills. As of early 2026, Treasury Bill rates might range from 18-22% per annum, depending on CBN policies and auction outcomes.
- Allowances/Benefits: Any regular allowances (e.g., transport, housing) or social welfare benefits.
For households with irregular income, such as freelancers, small business owners, or those in commission-based roles, calculating a consistent monthly income can be challenging. In such cases, it's often best to use an average of your past 3-6 months' net income or to budget based on your lowest expected income, saving any surplus from higher-income months. TrustAm has a dedicated article on How to Budget When Your Income Is Irregular that can provide more tailored strategies for this scenario.
It's important to be realistic and conservative when estimating income. Overestimating can lead to budget shortfalls and frustration. Once you have a clear, consolidated figure for your total net household income, you have the solid ground upon which to build your budget.
Key Budget Categories for Nigerian Families (2026 Edition)
For Nigerian families in 2026, effective budgeting requires categorizing expenses into essential and non-essential buckets, reflecting the unique costs of living in Nigeria. This includes core needs like housing, food, and transportation, alongside utilities, education, healthcare, and crucial savings, allowing for a comprehensive overview of where every naira is spent.
Understanding where your money goes is as important as knowing how much you earn. For a Nigerian household, expenses can be broadly divided into two types: Fixed Expenses (those that generally stay the same each month, like rent) and Variable Expenses (those that change, like food or entertainment). Here's a breakdown of common categories and what to consider:
1. Housing
- Rent/Mortgage: The biggest chunk for many. In 2026, a decent 2-bedroom apartment in areas like Yaba, Surulere, or Garki might cost between ₦400,000 - ₦600,000 annually, paid upfront, translating to a significant monthly allocation if you divide it. Outside Lagos, in places like Enugu or Kano, a similar apartment could be ₦200,000 - ₦350,000 annually.
- Service Charge: Common in gated estates, covering security, waste, cleaning of common areas.
- Utilities:
- Electricity (NEPA/PHCN): Depending on your meter type and band, this can range from ₦15,000 - ₦50,000+ monthly for a family, especially with increased tariffs (e.g., Band A could be ~₦75/kWh).
- Generator Fuel: Diesel or petrol for powering your home during outages. A major expense, easily ₦30,000 - ₦80,000+ monthly for regular use.
- Water: Borehole maintenance, water delivery, or utility bills.
- Waste Disposal: LAWMA or private waste management fees.
2. Food & Groceries
- Market Purchases: Buying fresh produce, proteins, and staples from local markets. This is often more cost-effective.
- Supermarket Runs: For packaged goods, toiletries, and specific items.
- Eating Out/Takeaway: Indulging in buka food, fast food, or restaurant meals. This is often an area for potential savings.
- Estimated for a family of 4 in 2026: ₦180,000 - ₦280,000 monthly.
3. Transportation
- Fuel (Petrol/Diesel): If you own a car, this is a major variable expense, with petrol around ₦750-₦800 per litre.
- Public Transport: Danfo, keke, BRT, or even inter-state travel. Daily fares can add up quickly (e.g., ₦300-₦500 per trip in Lagos).
- Ride-Hailing Apps: Uber, Bolt, etc., can be convenient but costly.
- Car Maintenance: Regular servicing, repairs, tyres.
4. Education
- School Fees: For children, often paid termly or annually. Divide by 12 for monthly budget allocation.
- Books & Supplies: Textbooks, notebooks, stationery.
- Extra Lessons/Tutorials: For WAEC, JAMB, or specific subjects.
- School Transport: If not covered by fees.
5. Healthcare
- Health Insurance: If you have a family plan.
- Medication: Over-the-counter drugs, prescriptions.
- Doctor Visits: Consultations, check-ups.
- Emergency Fund for Health: Crucial given out-of-pocket costs.
6. Personal Care & Lifestyle
- Toiletries & Cosmetics: Soap, toothpaste, hair products.
- Salon/Barbershop: Regular grooming.
- Clothing & Accessories: For the household.
- Entertainment: Cinema, outings, subscriptions (DSTV, Netflix, Spotify).
- Social Events (Owambes): These are a significant part of Nigerian culture. Budgeting for them is key to avoiding financial strain. Check out Budget for Owambe Season Without Going Broke for tips.
- Gifts & Donations: For family, friends, religious institutions.
7. Communications
- Mobile Airtime & Data: For all family members.
- Home Internet: Fiber optic or MiFi plans.
8. Debt Repayment
- Loans: Personal loans, car loans, business loans.
- Credit Card Payments: If applicable.
- Ajo/Esusu Contributions: If you're part of a traditional savings or lending cooperative.
9. Savings & Investments
- Emergency Fund: Aim for 3-6 months of living expenses.
- Retirement Savings: Pension contributions, personal investment plans.
- Specific Goals: Down payment for a house, car, child's education, starting a business.
- Investments: Treasury Bills, mutual funds, stocks, real estate.
10. Miscellaneous/Contingency
- Unexpected Expenses: Car breakdown, minor home repairs, forgotten bills. This category is crucial in Nigeria where things can go wrong unexpectedly.
By breaking down your expenses into these categories, you gain granular control and can see exactly where your money is going. This clarity is the first step towards making informed decisions about your spending and saving habits.
Crafting Your Monthly Budget Template: Step-by-Step Guide for Nigerians
Crafting your monthly budget template in Nigeria involves a systematic process of listing all income sources, meticulously tracking and categorizing every expense, and then allocating funds according to financial priorities. This step-by-step approach ensures a realistic and actionable budget that supports both daily needs and long-term financial goals.
Now that you understand your income and the key expense categories, it's time to put it all together. Here’s a practical, step-by-step guide to creating your own monthly budget template for your Nigerian household:
Step 1: Calculate Your Total Net Household Income
As discussed earlier, sum up all net income sources for the month. This is your total budget ceiling. For example, if you and your spouse earn ₦450,000 and ₦350,000 net respectively, and you have a side hustle bringing in an average of ₦100,000, your total net income is ₦900,000.
Step 2: Track Your Expenses Diligently
This is arguably the most crucial step. For at least one month (ideally two or three), track every single kobo spent by every member of the household. This includes small purchases like akara and bread, danfo fares, airtime top-ups, and large bills. You can use:
- A simple notebook and pen.
- Spreadsheets (Google Sheets, Excel).
- Budgeting apps like TrustAm, which can aggregate your bank accounts (via secure integrations like Mono) and automatically categorize your spending, making tracking effortless.
- USSD codes (*737#, *901#, *919#, *822# etc.) to check balances and transaction histories regularly.
Don't try to change your spending habits during this tracking period; just observe. The goal is to get an accurate picture of your actual spending.
Step 3: Categorize and Allocate Your Funds
Once you have a clear picture of your spending, assign each expense to one of the categories identified earlier. Then, begin to allocate your income to these categories. A popular guideline is the 50/30/20 Rule, adapted for the Nigerian context:
- Needs (50-60%): Essential expenses like rent, food, transportation, basic utilities, healthcare, and minimum debt payments. Given Nigeria's high cost of living, this might be closer to 60% for many families.
- Wants (20-30%): Discretionary spending like entertainment, eating out, new clothes, subscriptions, and owambes. This is where you have the most flexibility to cut back.
- Savings & Debt Repayment (10-20%): This includes your emergency fund, investment contributions, and any extra payments towards debt beyond the minimum.
Adjust these percentages to fit your unique household situation. For instance, a family paying high rent might see their "Needs" category take a larger percentage.
Step 4: Create Your Budget Template
Using a spreadsheet or a dedicated budgeting app, list your income at the top, followed by your expense categories. Fill in the allocated amounts for each. Ensure that your total allocated expenses and savings do not exceed your total net income. If they do, you need to go back and make cuts, starting from your "Wants" category.
Step 5: Monitor and Adjust Regularly
A budget isn't a one-time thing; it's a living document. At the end of each month, compare your actual spending against your budgeted amounts. Ask yourself:
- Did I overspend in any category? Why?
- Did I underspend? Can I reallocate that surplus?
- Are my allocations still realistic given current prices (e.g., fuel, market food)?
- Are my financial goals still being met?
Make necessary adjustments for the next month. This iterative process is key to long-term budgeting success. For a broader perspective on managing your finances, consider reading How to Budget on a Nigerian Salary in 2026: The Complete Guide.
Step 6: Automate Savings and Bill Payments
Once you've allocated funds for savings and critical bills, automate them. Set up standing orders for your savings contributions to a separate account or investment platform immediately after you get paid. Schedule automatic bill payments for rent, school fees, or loan repayments to avoid missing deadlines and incurring penalties. Most Nigerian banks (GTBank, Access, Zenith, UBA) offer these features through their mobile apps and internet banking portals.
By following these steps, you'll not only create a robust budget template but also develop the discipline needed to manage your money effectively in the challenging, yet opportunity-rich, Nigerian economy of 2026.
Practical Tips for Sticking to Your Budget in Nigeria (2026)
Sticking to a budget in Nigeria requires proactive strategies like meal planning, negotiating prices, utilizing public transport, and actively seeking out cost-effective alternatives for daily expenses. Involving the entire household and consistently reviewing spending habits are also crucial for long-term success.
Creating a budget is one thing; sticking to it is another, especially with the temptations and unexpected expenses that life in Nigeria often throws your way. Here are practical tips to help your household stay disciplined and achieve your financial goals in 2026:
- Embrace Meal Planning and Bulk Buying: Plan your family's meals for the week or month. Create a shopping list and stick to it when you go to the market or supermarket. Buying staples like rice, beans, yam, and garri in bulk when prices are favourable (e.g., during harvest seasons) can lead to significant savings. Consider joining an "ajo" or "esusu" group for bulk food purchases.
- Shop Smart at Local Markets: Instead of relying solely on supermarkets, visit local markets (e.g., Mile 12, Bodija, Onitsha Main Market) for fresh produce and provisions. Don't be afraid to haggle; it's part of the culture and can save you a few naira.
- Reduce "Wants" Spending: Identify areas in your discretionary spending where you can cut back. Can you cook more at home instead of eating out? Can you reduce the frequency of cinema visits or expensive weekend outings? Small cuts here can free up substantial funds for savings or debt repayment.
- Utilize Public Transport: If possible, opt for public transport (danfo, keke, BRT) for daily commutes instead of ride-hailing services or driving your personal car, which consumes costly fuel. Carpooling with colleagues is another excellent way to save.
- Conserve Energy: Be mindful of electricity consumption. Turn off lights and appliances when not in use. Consider energy-efficient bulbs. This can help reduce your NEPA/PHCN bills and generator fuel consumption.
- Set Clear Financial Goals: Having specific, measurable, achievable, relevant, and time-bound (SMART) goals can be a powerful motivator. Whether it's saving for a child's school fees, a down payment on land, or an emergency fund, clear goals keep you focused.
- Involve the Entire Household: Financial literacy starts at home. Educate your spouse and older children about the budget and why it's important. When everyone is on board, it becomes a collective effort, increasing the chances of success.
- Review and Adjust Regularly: The Nigerian economy is dynamic. What works one month might not work the next. Regularly review your budget (e.g., weekly quick check-ins, monthly deep dives) and make adjustments based on changes in income, expenses, or economic conditions.
- Build an Emergency Fund: This cannot be stressed enough. Having 3-6 months of living expenses saved in a separate, easily accessible account is your financial safety net against unexpected job loss, health emergencies, or sudden repairs. Without it, unforeseen events can quickly derail your budget and plunge you into debt.
- Use Budgeting Tools: Leverage technology. Apps like TrustAm can provide real-time insights into your spending, send budget alerts, and help you visualize your financial progress, making it easier to stick to your plan.
Sticking to a budget is a marathon, not a sprint. There will be good months and challenging ones. The key is consistency and the willingness to learn and adapt. With these tips, your Nigerian household can build resilience and achieve financial freedom.
Example Monthly Budget Template for a Nigerian Household (2026)
An example monthly budget for a Nigerian household in 2026, with a combined net income of ₦900,000, typically allocates about 55% to needs (rent, food, utilities), 25% to wants (entertainment, discretionary), and 20% to savings and debt repayment. This structure helps manage high living costs while prioritizing financial growth and stability.
Let's illustrate with a hypothetical scenario: A Nigerian couple, Mr. and Mrs. Adeleke, living in a decent area of Lagos (e.g., Surulere/Yaba) with two primary school-aged children. Their combined net monthly income is ₦900,000. They aim to follow an adapted 55/25/20 rule (Needs/Wants/Savings & Debt).
Household Income:
- Mr. Adeleke (Net Salary): ₦500,000
- Mrs. Adeleke (Net Salary + Side Gig): ₦400,000
- Total Net Income: ₦900,000
Monthly Expense Allocation:
A. Needs (Approx. 55% of Income = ₦495,000)
- Housing:
- Annual Rent (₦540,000 for a 2-bed flat): ₦45,000 (monthly allocation)
- Service Charge: ₦10,000
- Electricity (Estimated): ₦30,000
- Generator Fuel (Petrol): ₦40,000 (Based on 50 litres @ ₦800/litre, 2-3 times a month)
- Water/Waste Disposal: ₦5,000
- Sub-total Housing: ₦130,000
- Food & Groceries:
- Market Purchases (Staples, Fresh Produce): ₦120,000
- Supermarket (Packaged goods, toiletries): ₦40,000
- Sub-total Food: ₦160,000
- Transportation:
- Car Fuel: ₦50,000 (For Mrs. Adeleke's commute & errands)
- Public Transport (Mr. Adeleke's commute + Kids' school run): ₦30,000
- Car Maintenance Fund: ₦10,000
- Sub-total Transportation: ₦90,000
- Education:
- Children's School Fees (Annual ₦300,000 for 2 kids): ₦25,000 (monthly allocation)
- Books/Supplies Fund: ₦5,000
- Sub-total Education: ₦30,000
- Healthcare:
- Health Insurance Premium: ₦15,000
- Medication/Contingency: ₦10,000
- Sub-total Healthcare: ₦25,000
- Communications:
- Internet (Home WiFi): ₦15,000
- Airtime/Data (Both Adults): ₦10,000
- Sub-total Communications: ₦25,000
- Miscellaneous/Contingency: ₦35,000 (For unexpected small expenses)
- Total Needs: ₦495,000
B. Wants (Approx. 25% of Income = ₦225,000)
- Personal Care:
- Salon/Barbershop: ₦15,000
- Toiletries (beyond basic supermarket buys): ₦10,000
- Sub-total Personal Care: ₦25,000
- Entertainment & Social:
- Family Outings/Cinema: ₦20,000
- Eating Out/Takeaway: ₦30,000
- DSTV/Netflix Subscriptions: ₦15,000
- Owambe Fund (monthly allocation for future events): ₦50,000
- Sub-total Entertainment: ₦115,000
- Clothing & Personal Shopping: ₦40,000
- Gifts & Donations: ₦25,000
- Total Wants: ₦205,000 (Slightly under budget, creating a small surplus for flexibility or extra savings.)
C. Savings & Debt Repayment (Approx. 20% of Income = ₦180,000)
- Emergency Fund: ₦60,000 (Aiming for 3-6 months of living expenses)
- Investment (Mutual Funds/Treasury Bills): ₦70,000
- Debt Repayment (e.g., small personal loan): ₦50,000
- Total Savings & Debt: ₦180,000
Summary:
- Total Net Income: ₦900,000
- Total Needs: ₦495,000
- Total Wants: ₦205,000
- Total Savings & Debt: ₦180,000
- Total Outflow (Needs + Wants + Savings & Debt): ₦880,000
- Remaining Balance: ₦20,000 (This small surplus can roll over to savings or be used for minor unexpected expenses next month, providing a buffer.)
This example demonstrates how a Nigerian household can allocate its funds. Remember, these figures are estimates for 2026 and would need to be adjusted based on your specific location (e.g., living in Port Harcourt or Abuja would have different rent and transport costs), family size, and income level. For more specific budget examples, check out our articles like How to Budget on ₦500,000 in Enugu in 2026 or How to Budget on ₦200,000 in Lagos in 2026.
Conclusion
Creating and consistently using a monthly budget template is undoubtedly one of the most powerful tools a Nigerian household can wield in 2026 to achieve financial stability and growth. In an economic climate marked by volatility and rising costs, a budget provides clarity, control, and peace of mind. It transforms the abstract concept of "managing money" into a concrete, actionable plan that empowers you to make intentional decisions about every naira.
Remember, your budget is a dynamic document. It should evolve with your income, expenses, and life circumstances. Be patient with yourself, celebrate small wins, and don't get discouraged by occasional setbacks. The journey to financial freedom is a marathon, and your budget is the pace car that keeps you on track.
Ready to take control of your household finances? Download the TrustAm app today. Our AI-powered financial advisor, spending analytics, and bank aggregation features make budgeting and tracking your money effortless, helping your Nigerian household thrive in 2026 and beyond.
Frequently Asked Questions
How do I create a simple monthly budget for my family in Nigeria?
To create a simple monthly budget for your family in Nigeria, first, calculate your total net monthly income from all sources. Next, list all your fixed expenses like rent and loan repayments, and estimate your variable expenses such as food, transportation, and utilities. Subtract your total expenses from your total income, ensuring you allocate funds for savings and debt repayment. Review and adjust this budget monthly to reflect changes in income or spending.
What are the essential budget categories for a Nigerian household?
Essential budget categories for a Nigerian household typically include housing (rent, service charge, electricity, generator fuel, water), food and groceries, transportation (fuel, public transport), education (school fees, supplies), healthcare, communications (internet, airtime), and debt repayment. It's also crucial to include a dedicated category for savings, including an emergency fund and investments, and a contingency fund for miscellaneous expenses.
How much should a Nigerian family budget for food monthly in 2026?
The amount a Nigerian family should budget for food monthly in 2026 varies significantly based on family size, location, and dietary habits, but generally ranges from ₦180,000 to ₦280,000 for a family of four. This estimate covers a mix of market purchases for fresh produce and staples, and some supermarket runs for packaged goods. Smart shopping, meal planning, and buying in bulk can help manage these costs effectively.
How can I reduce household expenses in Nigeria?
To reduce household expenses in Nigeria, you can implement several strategies: plan meals to avoid impulse food purchases and waste, utilize local markets for cheaper groceries, opt for public transport or carpooling, conserve electricity to lower utility bills, and critically review discretionary spending on entertainment and social events. Additionally, consider negotiating prices where possible and exploring bulk purchasing opportunities.
What is the 50/30/20 budget rule and how does it apply in Nigeria?
The 50/30/20 budget rule suggests allocating 50% of your net income to Needs (essentials), 30% to Wants (discretionary spending), and 20% to Savings and Debt Repayment. In Nigeria, due to high living costs and inflation, this rule often needs adaptation, with Needs potentially taking up 55-65% of income, Wants 20-25%, and Savings/Debt 10-20%. The key is to adjust these percentages to fit your unique household income and expense structure while prioritizing savings.
Should I include my children in the budgeting process?
Yes, including your children, especially older ones, in the budgeting process is highly recommended. It teaches them valuable financial literacy skills, helps them understand the family's financial situation, and fosters a sense of collective responsibility. When children understand why certain spending limits are in place, they are more likely to cooperate and contribute to the household's financial goals.
How can TrustAm help with my household budget?
TrustAm can significantly help with your household budget by providing an AI-powered financial advisor that offers personalized insights and recommendations. It also features spending analytics to automatically categorize and track your expenses across all your bank accounts (via secure integrations), making it easier to see where your money goes. Furthermore, TrustAm's tools can help you set and monitor budget limits, identify areas for savings, and visualize your progress towards financial goals.
Find verified service providers
Verified providers. Payment held safe until the job is done. Reviews only from real, paid bookings.
Download TrustAm
AI-powered budgeting, instant P2P payments, and escrow protection. Built for Nigeria.
Or get a download link sent to your phone
Chisom Anen
Founder and CEO of TrustAm. Building Nigeria's reputation marketplace for verified service providers. Reviews unlock only after real payments.
Disclaimer: This article is for informational purposes only and does not constitute financial advice. Always consult a qualified financial professional before making major financial decisions.
Disclosure: This article is published by TrustAm, a financial technology company. Some links in this article may direct to our own products.
Sources & References
- National Bureau of Statistics — Consumer Price Index— nigerianstat.gov.ng
- Central Bank of Nigeria — Monetary Policy Rate— cbn.gov.ng
- BudgIT — Budget Tracking— budgit.org
- Federal Mortgage Bank of Nigeria— fmbn.gov.ng
Related Articles
Free Tools You Might Find Useful
Try these free calculators and tools related to this article.
Lagos Budget
Plan your monthly budget for living in Lagos with realistic cost breakdowns.
Use free tool →Abuja Budget
Plan your monthly budget for living in Abuja with realistic cost breakdowns.
Use free tool →Ibadan Budget
Plan your monthly budget for living in Ibadan with affordable cost breakdowns.
Use free tool →PH Budget
Plan your monthly budget for living in Port Harcourt, Nigeria.
Use free tool →