Who Should You Give Goods on Credit? A Simple Rule for Foodstuff Store Owners
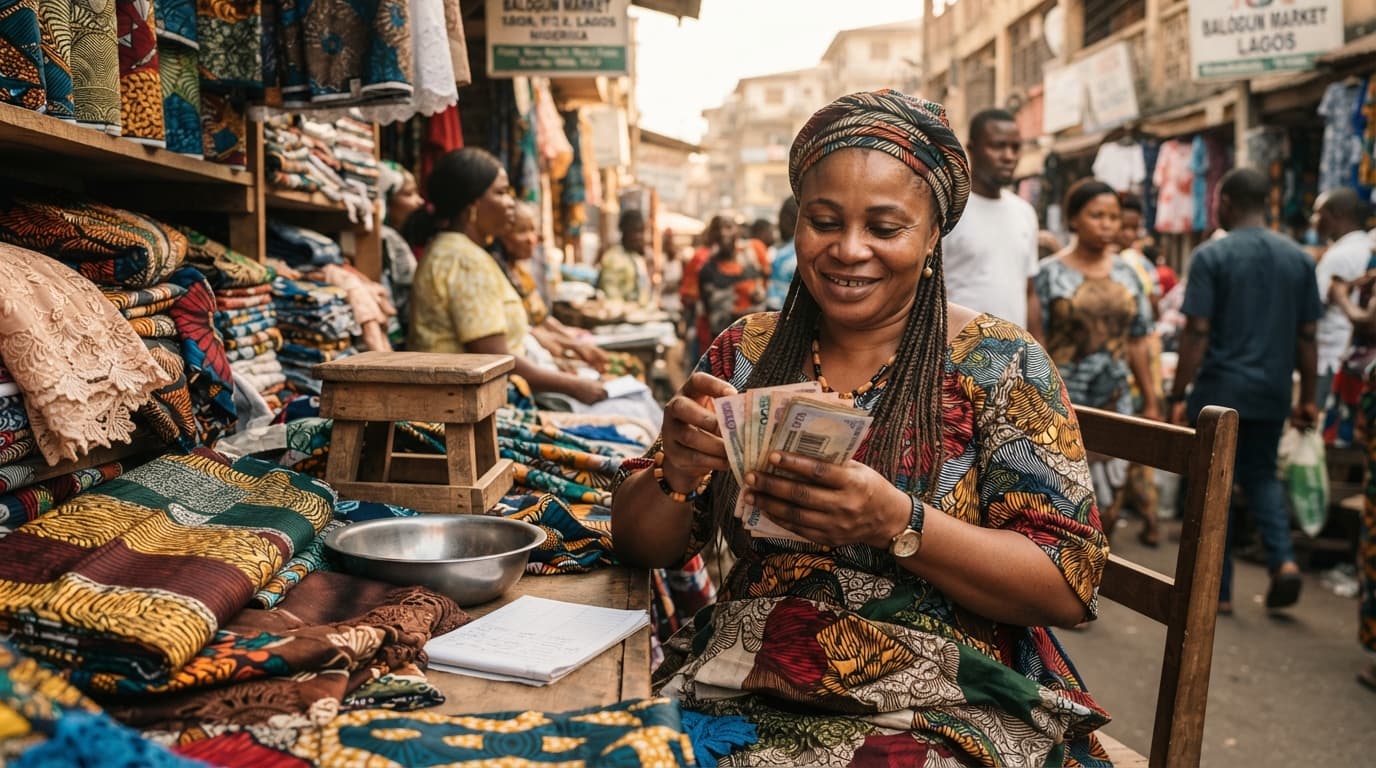
Mama Ngozi, your foodstuff stall in the market is always busy. Today, a customer, Mrs. Adebayo, comes in needing bags of rice and some yam. She says she’ll pay you next week when she sells some of her own goods. You know her, she’s been buying from you for years. But giving credit can be tricky. How do you decide who to trust with your goods when cash is tight?
Overview & Key Takeaways
Learn a simple, practical rule for deciding which customers you can safely give credit to in your foodstuff store. Understand the risks and how to manage them.
- Always start with customers who pay on time.
- Look for customers who buy regularly and consistently.
- Consider the customer's perceived ability to pay based on their own business.
- Never give credit beyond what you can afford to lose.
- Use tools to track who owes you, even if it’s just a note.
Giving credit is like lending your hard-earned money. If the customer pays back, it’s good business. If they don’t, your profit disappears, and you might even lose money you invested. For foodstuff sellers, where goods can be expensive like bags of rice or cartons of oil, this is serious.

Who Can You Trust with Your Goods on Credit?
As a foodstuff seller, you want to help your regular customers, but you also need to protect your business. A simple rule to follow is this: **Give credit only to customers who have a proven track record of paying you back on time, and only for amounts you can afford to lose.** Let’s break this down.
First, think about your current customers. Who are the ones that always pay you cash, or pay you back exactly when they say they will? These are your best customers. They show respect for your business and your money. If you’re going to offer credit, it should be to these reliable people first. For them, you might consider selling on credit, but still be careful.
Customers Who Pay On Time
These are gold! They don’t need you to beg or remind them. When they say they’ll pay next Tuesday, they do. This shows they are responsible and have a good plan for their own money. For these customers, you can be more comfortable offering a small amount of credit. Maybe a bag of rice, or some essential items they need. If they pay back as promised, you can slowly increase the credit limit for them. This builds trust on both sides.
Regular, Consistent Buyers
Look at who buys from you most often. Are they buying small amounts every day, or big amounts once a month? Consistency is key. A customer who buys a carton of noodles every week and always pays cash is a safer bet for credit than someone who sometimes buys a lot and sometimes buys nothing. Their regular purchases show they have a steady income or business. If they ask for credit, consider their usual spending habits. If they normally spend ₦5,000 a week, maybe offer them credit of ₦10,000 for a week. It’s a small step up, not a huge leap.
Customers Who Can Afford to Pay You Back
This is about looking at the customer’s own situation. If you sell foodstuffs, and your customer also sells foodstuffs, or perhaps runs a small eatery, you can often see if their business is doing well. Are they always busy? Do they have new stock? If their business looks like it’s thriving, they are more likely to be able to pay you back. But be careful not to judge just by appearance. Someone might look prosperous but be in debt themselves. It’s better to rely on their payment history with you.

The Golden Rule: Only Lend What You Can Lose
This is the most important part. No matter how much you trust someone, things can go wrong. They might fall sick, their business might face a sudden problem, or maybe they just forget. You must decide before giving any credit, “What is the maximum amount I am willing to lose if this customer cannot pay me back?”
For a small foodstuff seller, this amount might be the cost of one or two bags of rice. For a larger one, it might be more. Never give credit that will cripple your own business if it’s not repaid. Think of it like this: If you give ₦20,000 worth of goods on credit and the customer doesn't pay, can your business still survive? If the answer is no, then you have given too much credit. Always protect your capital first. This is why tracking customer debt is so important, even if it’s just a simple note.
What If They Can’t Pay?
Sometimes, even good customers run into trouble. If you have a customer who usually pays but suddenly can’t, what do you do? First, talk to them. Understand their situation. Maybe they can pay a little now and the rest later. Or perhaps they can pay in installments. Be firm but understanding. If you have been keeping good records, you know exactly how much they owe and for how long. This makes the conversation easier. Remember the article on how to chase customers politely. It’s about getting your money back without losing the customer if possible.
Making Credit Decisions Easier with TrustAm
Deciding who to give credit to can be stressful, especially when you are busy serving customers. Imagine if you could instantly see who owes you what, and how long they have owed you, right on your phone? This is where tools like TrustAm can help.
With TrustAm, you can record every credit sale. When a customer buys on credit, you just tell TrustAm what they bought and who they are. Later, when they pay, you record the payment. It automatically updates the customer’s balance. You can even set up automatic reminders for customers when their payment is due. This means you spend less time worrying about who owes what and more time selling.
TrustAm is not an app to download, it works directly inside WhatsApp. You can send payment requests, record cash sales, and manage your debts all from your favourite messaging app. This means your records are always up-to-date without you needing to stop what you’re doing to write things down. It helps you know exactly who you can extend credit to, and who you should probably ask for cash upfront. It helps you keep track of all your sales, whether they are cash or credit, and see a summary of your business performance. This is like having an assistant that helps you manage your money and your customers without any extra work.
Quick Tips for Giving Credit Wisely:
- Start Small: Offer credit for small amounts first.
- Know Your Customer: Rely on their payment history with you.
- Set Limits: Never lend more than you can afford to lose.
- Record Everything: Use a notebook, a spreadsheet, or an app to track every credit sale and payment.
- Communicate: Talk to customers if they are late with payments.
- Get Paid First: For new customers or large purchases, always insist on cash.
Giving credit can be a good way to build customer loyalty and increase sales, but it needs to be done smartly. By following the rule of only lending what you can afford to lose and prioritizing reliable customers, you can manage credit risks effectively and keep your foodstuff store thriving.
Frequently Asked Questions
How do I know if a customer is reliable for credit?
A reliable customer is someone who consistently pays their debts on time. Look for customers who have a history of paying you promptly for previous purchases. They should also be a regular buyer, showing consistent business activity.
What if I give credit and the customer doesn't pay?
If a customer doesn't pay, first try to communicate with them politely to understand the situation and arrange a payment plan. If that doesn't work, you may need to stop giving them credit and focus on recovering the outstanding amount. Using a system to track debts makes this process easier.
How much credit should I offer a new customer?
For new customers, it's best to avoid giving credit altogether. If you must, start with a very small amount that you are comfortable losing. Always insist on cash payment for initial transactions until you build trust and a payment history.
Can I give credit to family and friends?
Giving credit to family and friends can be risky for your business. While you may trust them personally, it's important to treat all transactions professionally. Set clear payment terms and stick to them, or consider not offering them credit to avoid straining relationships.
How can I track who owes me money easily?
You can use a simple notebook, a spreadsheet on your phone, or a dedicated business tool like TrustAm. TrustAm allows you to record credit sales directly in WhatsApp, automatically tracks balances, and can even send polite reminders to customers, making debt tracking much simpler.
Find verified service providers
Verified providers. Payment held safe until the job is done. Reviews only from real, paid bookings.
Download TrustAm
AI-powered budgeting, instant P2P payments, and escrow protection. Built for Nigeria.
Or get a download link sent to your phone
Chisom Anen
Founder and CEO of TrustAm. Building Nigeria's reputation marketplace for verified service providers. Reviews unlock only after real payments.
Disclaimer: This article is for informational purposes only and does not constitute financial advice. Always consult a qualified financial professional before making major financial decisions.
Disclosure: This article is published by TrustAm, a financial technology company. Some links in this article may direct to our own products.
Sources & References
- Federal Inland Revenue Service— firs.gov.ng
- Corporate Affairs Commission— cac.gov.ng
- Small and Medium Enterprises Development Agency— smedan.gov.ng
- Central Bank of Nigeria, Monetary Policy— cbn.gov.ng
Related Articles
Free Tools You Might Find Useful
Try these free calculators and tools related to this article.
Invoice Generator
Generate professional invoices for your Nigerian business or freelance work.
Use free tool →Receipt Generator
Generate payment receipts for completed services in Nigeria.
Use free tool →Quote Generator
Generate service quotations for clients in Nigeria.
Use free tool →Contract Generator
Generate basic service agreements for Nigerian service providers.
Use free tool →